Southwest Michigan Financial, LLC does not offer every plan available in your area. Currently we represent 6 organizations which offer 32 products in your area. Any information we provide is limited to those plans. Please contact Medicare.gov, your local State Health Insurance Program (SHIP) office, or call 1-800-MEDICARE to get information on all your options.
Quick Take
- Network & Formulary Shift Audit: Medicare Advantage and Part D plans adjust doctor networks, hospital partnerships, and prescription drug formularies annually. Unchecked plans risk sudden out-of-network costs or altered drug coverage.
- 2026 Inflation Reduction Act Savings: Beneficiaries benefit from federal provisions including a $2,100 out-of-pocket Part D cap, $35/month insulin limits, $0 vaccines, and the Medicare Prescription Payment Plan to smooth costs over 12 months.
- Defusing IRMAA Tax Cliffs: Crossing Medicare income thresholds by just $1 triggers non-progressive monthly premium surcharges across Parts B and D. Proactive tax planning prevents unexpected penalties.
Every year, Medicare plans adjust their formularies, copays, deductibles, and doctor networks—and under current Inflation Reduction Act guidelines, prescription drug rules have changed dramatically. While federal provisions like the $2,100 out-of-pocket Part D cap and $35/month insulin limits offer built-in protections, staying in an unoptimized plan can still leave thousands of dollars in avoidable healthcare costs on the table.
A successful Medicare review begins with accurate information. Whether you are reviewing a Medicare Advantage plan or coordinating Original Medicare with a Medigap policy and stand-alone Part D coverage, auditing your doctors, pharmacy choices, and medications in advance ensures no details fall through the cracks.
After you read the information below, use the Medicare Annual Review Intake Worksheet to organize your healthcare profile before meeting with your advisor. Completing these sections ahead of time allows us to instantly identify network alignment, run precise prescription cost models, and locate potential savings for the coming year.
A 10-Minute Self-Assessment to Ensure Your Coverage, Cash Flow, and Legacy Remain Fully Protected.
Step 1: The Health & Network Checkup
Health networks and drug formularies change every year. Put a check mark next to the statements that apply to you:
- [ ] My Primary Doctors: All of my primary care physicians and specialists are still in my plan’s network for the upcoming year.
- [ ] Preferred Health Systems: My preferred local hospital systems (e.g., Bronson, Beacon, Corewell, Trinity, Henry Ford, McLaren) accept my coverage without out-of-network penalties.
- [ ] Medication Formulary: Every daily prescription I take is listed on my plan’s current drug list (formulary) with no new restrictions (such as step therapy or prior authorization requirements).
- [ ] Pharmacy Choice: My regular pharmacy is classified as a “Preferred Cost-Sharing Pharmacy” under my drug plan to guarantee the lowest copays.
- [ ] Unknown: I am unsure how to answer one or more of the sections above and need more information.
Self-Audit Result: If you left any box unchecked above, your plan may expose you to sudden out-of-pocket costs or network disruptions in the coming year.
From the Experts
“Navigating Medicare across Southwest Michigan isn’t just about choosing a plan—it’s about making sure your trusted doctors at Bronson, Beacon or Corewell remain in-network without unexpected surprises. Taking ten minutes to complete this worksheet allows us to audit your healthcare coverage against real-world changes before Open Enrollment closes, ensuring your local care team stays intact.” — Justin Henrich, Southwest Michigan Financial
Step 2: The 2026 Inflation Reduction Act (IRA) Cash Flow Check
Federal drug coverage rules have undergone landmark updates. Check off what you know about your options:
[ ] The $2,100 Out-of-Pocket Cap: I know whether my total prescription spending will hit or exceed the federal $2,100 annual out-of-pocket maximum.
[ ] High-Cost Drug Savings: I am aware of my medications that fall under Medicare-negotiated price reductions (e.g., Eliquis, Xarelto, Jardiance, Farxiga, Entresto, Januvia).
[ ] Monthly Payment Smoothing (MPPP): I know how to use the Medicare Prescription Payment Plan if I want to spread my large upfront pharmacy bills into equal monthly payments throughout the year instead of paying all at once.
[ ] $35 Insulin & $0 Vaccines: I am paying no more than $35/month for covered insulin products and $0 out-of-pocket for ACIP-recommended vaccines (like Shingrix or RSV).
[ ] Unknown: I am unsure how to answer one or more of the sections above and need more information.
Self-Audit Result: If you are spending heavily at the pharmacy counter early in the year, you may be missing out on federal payment-smoothing tools or lower-tier formulary options.
Step 3: The IRMAA & “Single Dollar” Tax-Cliff Test
Income-Related Monthly Adjustment Amounts (IRMAA) hit high-net-worth households with strict, non-progressive premium surcharges based on income from two years prior.
[ ] 2-Year Lookback Income: My 2024 Modified Adjusted Gross Income (MAGI) was safely below the $109,000 (Single) or $218,000 (Married Filing Jointly) threshold.
[ ] Municipal Bond Audit: I have calculated my tax-exempt municipal bond interest, knowing it must be added back into my AGI when Medicare calculates my IRMAA thresholds.
[ ] Work Status Change (SSA-44): If I retired, scaled back work hours, or lost income in 2024 or 2025, I have evaluated filing Form SSA-44 to appeal and lower my current Medicare surcharges.
[ ] Roth Conversion Buffer: If I am planning a Roth IRA conversion this year, I have calculated my exact headroom to ensure the conversion doesn’t trigger a $2,000+ Medicare surcharge two years from now.
[ ] Unknown: I am unsure how to answer one or more of the sections above and need more information.
Self-Audit Result: Crossing an IRMAA threshold by just $1 triggers mandatory monthly surcharges across both Part B and Part D for the entire calendar year.
Step 4: The Results: Your Personal Medicare Scorecard
Calculate your score based on Steps 1–3 above:
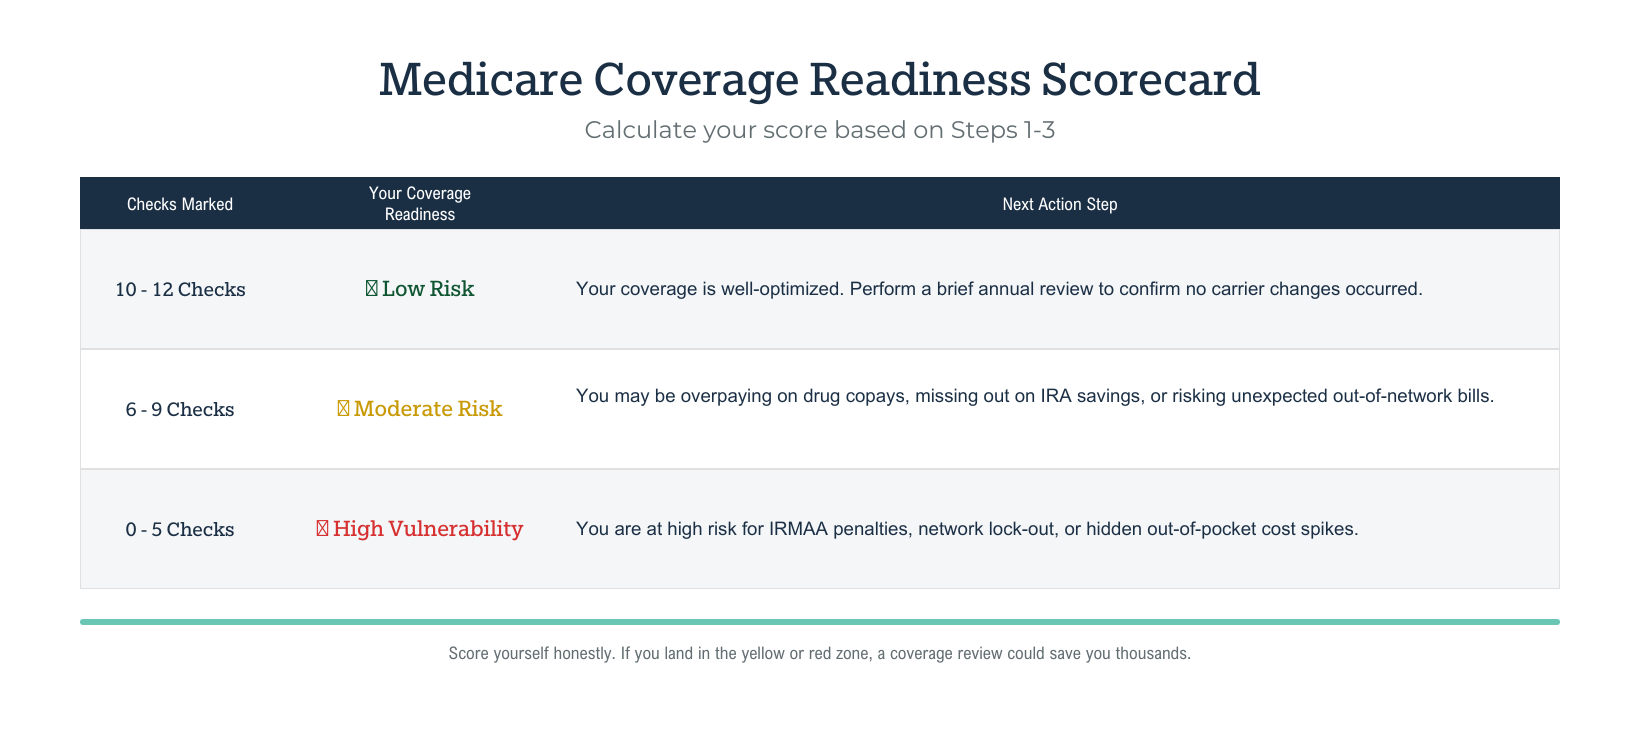
10 – 12 Checks
Low Risk
Your coverage is well-optimized. Perform a brief annual review to confirm no carrier changes occurred.
6 – 9 Checks
Moderate Risk
You may be overpaying on drug copays, missing out on IRA savings, or risking unexpected out-of-network bills.
0 – 5 Checks
High Vulnerability
You are at high risk for IRMAA penalties, network lock-out, or hidden out-of-pocket cost spikes.
Step 5: Action & Review Notes
Use this space to write down your top 3 questions or concerns before meeting with your advisor:
- Medications I want audited for lower copays: ________________________________________
- Upcoming health/doctor changes in the next 12 months: __________________________________
- Income or retirement events that might trigger an IRMAA surcharge: ____________________
From the Experts
“Failing to audit and update your Medicare coverage during the annual enrollment period is one of the most expensive mistakes a retiree can make. When drug plans or Medicare Advantage networks quietly adjust their formularies and tiers, staying on autopilot can subject you to massive out-of-pocket price spikes and out-of-network fines that could have easily been avoided with a 10-minute review.” — Justin Henrich, Southwest Michigan Financial
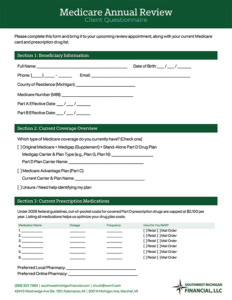 To schedule an Annual Medicare Review with Our Team, Download and Complete this Medicare Annual Review Intake Worksheet
Taking 10 minutes to complete this intake worksheet transforms your annual Medicare review from a guessing game into a precise, data-driven financial audit. By mapping out your exact medication dosages, primary care networks, and supplemental benefit preferences, we can ensure your coverage continues to safeguard both your physical health and your retirement cash flow.
Once you have filled out your worksheet, bring it along with your Medicare card and current prescription drug bottles to your scheduled review session. If you experience an unexpected diagnosis or income change during the year, we can immediately adjust your strategy to keep your out-of-pocket expenses minimized.
Takeaway
Your healthcare coverage isn’t a static, set-it-and-forget-it expense. Annual reviews ensure your plan actively adapts to federal policy updates, drug formulary shifts, and your personal health needs.
Click Here to Access Our Medicare Resource Center or Schedule Your 15-Minute Medicare Strategy Call to review your completed worksheet with an independent fiduciary.
Southwest Michigan Financial, LLC is not affiliated with or endorsed by the government or federal Medicare program. Justin Henrich is a licensed Medicare agent of Medicare Advantage organizations and prescription drug plans with Medicare contracts.
This blog is created and authored by Chuck Henrich (Content Creator) and is published and provided for informational and entertainment purposes only. The information in the Blog constitutes the Content Creators own opinions and it should not be regarded as a description of services provided by Southwest Michigan Financial, LLC. The opinions expressed in the Blog are for general informational purposes only and are not intended to provide specific advice or recommendations for any individual or on any specific security or investment product. It is only intended to provide education about the financial industry. The views reflected in the commentary are subject to change at any time without notice.
Nothing on this Blog constitutes investment advice, performance data or any recommendation that any security, portfolio of securities, investment product, transaction or investment strategy is suitable for any specific person. The Content Creator and Southwest Michigan Financial, LLC assumes no responsibility or liability for any consequences resulting directly or indirectly for any action or inaction you take based on or made in reliance of the information, services or materials provided within this blog.